
Why you should know this
Stablecoins are often described as “digital dollars.” That phrase is convenient and incomplete. A stablecoin is a token designed to maintain a reference value through an issuer, reserve, redemption mechanism, market incentives or another structure. It is not automatically a bank deposit, legal tender or government guarantee.
For cross-border use, the relevant question is not only whether the token moved quickly. It is whether the intended person can receive, redeem or convert it safely under applicable rules and at an acceptable final cost.
The stablecoin stack
A practical stablecoin arrangement can involve:
- Reference asset: commonly a fiat currency such as the US dollar.
- Issuer or protocol: creates and manages the token under defined rules.
- Stabilization mechanism: reserves, redemption, collateral or another design.
- Blockchain network: records token transfers.
- Wallet or custodian: controls the user’s keys or account.
- Exchange or off-ramp: converts between the token and local currency.
- Banking and payment rails: deliver or receive fiat.
- Legal and compliance framework: affects issuance, transfer, custody and redemption.
A strong network cannot repair weak reserves. Strong reserves cannot correct a wrong address. A liquid exchange cannot guarantee a bank credit. We review the whole stack.
Stablecoins in a transfer
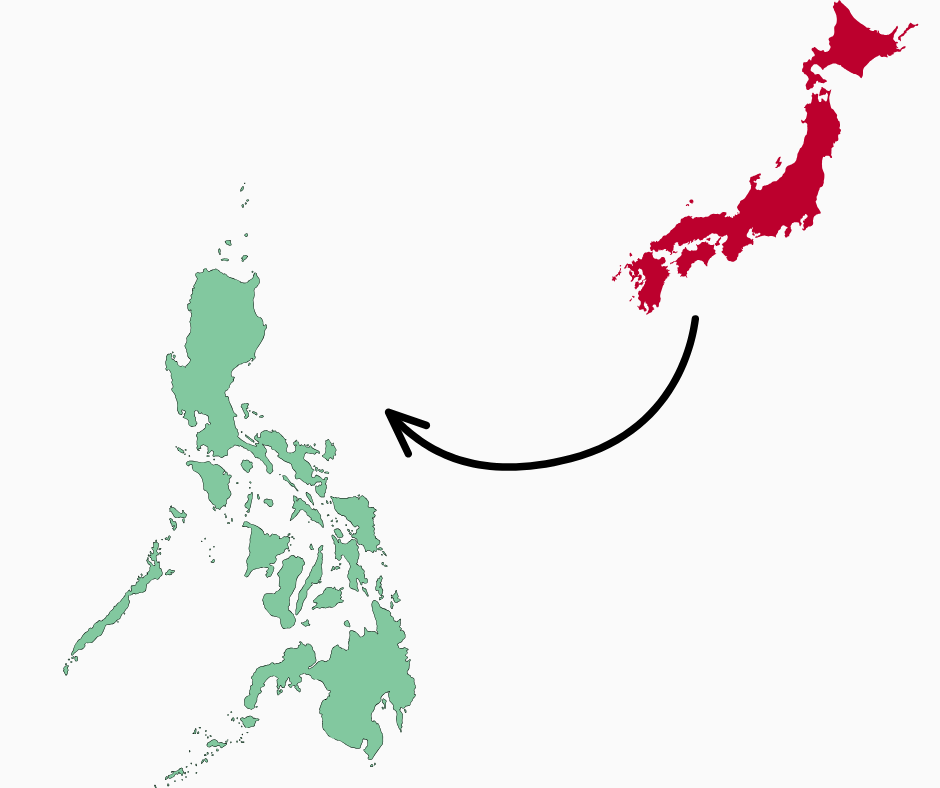
A hypothetical route may be:
JPY → regulated service or supported funding route → stablecoin → blockchain network → Philippine VASP or wallet → PHP conversion → bank or e-wallet.
The token can reduce exposure to a volatile crypto asset during transfer, but it may add:
- issuer and reserve risk;
- network and smart-contract risk;
- custody risk;
- depeg and liquidity risk;
- Travel Rule and screening requirements;
- local conversion and FX risk;
- provider, bank and jurisdiction dependencies.
BIS analysis notes that the stablecoin’s peg currency may differ from both the sender’s and recipient’s domestic currencies. That mismatch creates FX and policy considerations even when the token remains near its peg.
Network identity still matters
The same stablecoin name may exist on several networks or through bridged versions. The recipient must support the exact token contract or issuer and the exact network. A lower network fee does not make an unsupported deposit correct.
Wrapped or bridged tokens can introduce another issuer, bridge or smart-contract dependency. Read the receiving service’s current deposit instructions and use a valid test.
Practice check — no money needed

Draw a stablecoin transfer as three layers: token/issuer, blockchain network and provider. Mark one failure or value-risk point in each relevant layer.
The goal is not to memorize a slogan. If you can explain the route or decision, name the main limitation, and identify what evidence you would need before using real money, the lesson has done its job.
How this connects to market mastery
Advanced participants examine reserve liquidity, redemption arbitrage, market depth, issuer concentration and peg stress. The beginner stack is the same analytical model in simpler form: identify every promise and the mechanism expected to support it.


