
Why you should know this
Stablecoins are often described as “digital dollars.” That phrase is convenient and incomplete. A stablecoin is a token designed to maintain a reference value through an issuer, reserve, redemption mechanism, market incentives or another structure. It is not automatically a bank deposit, legal tender or government guarantee.
For cross-border use, the relevant question is not only whether the token moved quickly. It is whether the intended person can receive, redeem or convert it safely under applicable rules and at an acceptable final cost.
The stablecoin stack
A practical stablecoin arrangement can involve:
- Reference asset: commonly a fiat currency such as the US dollar.
- Issuer or protocol: creates and manages the token under defined rules.
- Stabilization mechanism: reserves, redemption, collateral or another design.
- Blockchain network: records token transfers.
- Wallet or custodian: controls the user’s keys or account.
- Exchange or off-ramp: converts between the token and local currency.
- Banking and payment rails: deliver or receive fiat.
- Legal and compliance framework: affects issuance, transfer, custody and redemption.
A strong network cannot repair weak reserves. Strong reserves cannot correct a wrong address. A liquid exchange cannot guarantee a bank credit. We review the whole stack.
Reserve-backed stablecoins
A reserve-backed design seeks to support outstanding tokens with assets held by or for the issuer. The quality of that support depends on:
- reserve composition and credit quality;
- liquidity and maturity;
- custody and segregation;
- frequency and scope of assurance or audit;
- legal claim and redemption rights;
- who is eligible to redeem directly;
- fees, limits and timing;
- treatment during stress or insolvency.
FSB recommendations emphasize robust governance, transparent information, effective stabilization and redemption. They are standards for authorities, not a guarantee that every token meets them.
Other designs
Crypto-collateralized or algorithmic designs may use over-collateralization, liquidation, incentives or market arbitrage. Their risk can behave differently during stress.
A label such as “decentralized” does not remove dependency on smart contracts, oracles, governance, collateral liquidity and market confidence. Beginners should not assume that every stablecoin can be redeemed one-for-one by every holder.
Peg, market price and redemption are different
Peg or reference: the value the token is designed to track.
Market price: what buyers and sellers will pay now on a specific venue.
Redemption value: what an eligible holder can receive from the issuer or authorized route under current terms.
A token can trade below its peg even if redemption is available, because access, time, fees and confidence differ. It can trade near the peg while direct redemption remains unavailable to a particular retail user.
What depeg risk means
A depeg occurs when the market value moves materially away from the reference. Causes can include reserve concerns, redemption delays, legal action, banking disruption, market panic, low liquidity, technical failure or loss of confidence.
If a stablecoin moves from US$1.00 to US$0.97, a holder has a 3% market-value gap before other fees and FX. A rapid discount can also widen spreads and reduce off-ramp liquidity. “Stable” describes an objective, not immunity from loss.
Stablecoins in a transfer
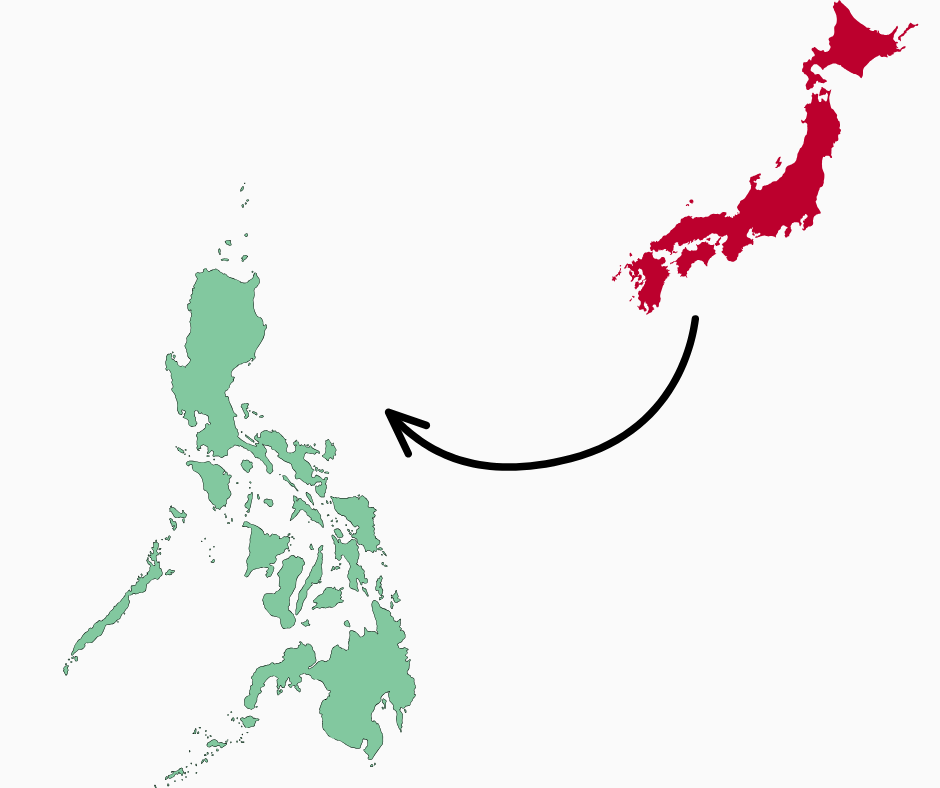
A hypothetical route may be:
JPY → regulated service or supported funding route → stablecoin → blockchain network → Philippine VASP or wallet → PHP conversion → bank or e-wallet.
The token can reduce exposure to a volatile crypto asset during transfer, but it may add:
- issuer and reserve risk;
- network and smart-contract risk;
- custody risk;
- depeg and liquidity risk;
- Travel Rule and screening requirements;
- local conversion and FX risk;
- provider, bank and jurisdiction dependencies.
BIS analysis notes that the stablecoin’s peg currency may differ from both the sender’s and recipient’s domestic currencies. That mismatch creates FX and policy considerations even when the token remains near its peg.
Network identity still matters
The same stablecoin name may exist on several networks or through bridged versions. The recipient must support the exact token contract or issuer and the exact network. A lower network fee does not make an unsupported deposit correct.
Wrapped or bridged tokens can introduce another issuer, bridge or smart-contract dependency. Read the receiving service’s current deposit instructions and use a valid test.
Settlement is more than blockchain finality
A network may record the transfer within minutes or seconds. Final usable settlement can still wait for:
- provider confirmation requirements;
- internal crediting;
- identity or Travel Rule data;
- transaction monitoring;
- stablecoin conversion liquidity;
- PHP Withdrawal processing;
- bank or e-wallet credit.
Advertised network speed is therefore not the same as sender-to-household delivery.
Philippine scenario: a stable token, changing PHP
Maria sends a dollar-referenced stablecoin when the USD/PHP comparison rate is at one level. By the time Liza converts, PHP has moved and the provider’s sell quote contains a spread.
The stablecoin stayed close to one US dollar, yet the final PHP changed. Maria and Liza compare the executable PHP quote, not only the token peg. They also confirm the receiving network and all fees before the main transfer.
Liza is free to receive PHP without holding or trading the token.
What to inspect before use
- Who issues or governs the token?
- What supports the target value?
- What reserve information is available and current?
- Who has a legal redemption claim?
- Can the actual user redeem, or only sell through a market?
- On which network and contract will the token move?
- Which provider converts it to PHP?
- What happens during a depeg, halt or issuer action?
- Are freeze, blacklist or contract-control powers disclosed?
- What total loss remains affordable?
Do not treat an “attestation” as an unlimited conclusion. Read its scope, date, reporting period, verifier and limitations.
Stablecoin Scam or Legit?
A stranger promises a 15% monthly “stablecoin remittance yield” with no risk because the token stays at one dollar. The claim combines price stability with an investment return that requires separate explanation and evidence. Stop. Transfer utility does not create guaranteed yield.
Four ways a “stable” route can break
Issuer failure: reserves, governance, banking access or operations may not support redemption as expected. The market price can move away from the reference asset.
Market-liquidity failure: the token may remain redeemable in theory while the chosen venue has a wide spread or too little demand. A PHP conversion can therefore produce less than the simple peg calculation suggests.
Network or custody failure: the token may work as designed, but a wrong address, unsupported network, compromised key or suspended provider can prevent use.
Corridor failure: both providers may support the token individually while the particular origin, destination, customer type or data flow is unavailable. Technical compatibility is not legal or operational availability.
These failures are independent. A token staying near its peg does not prove the remittance route will complete.
Read a stablecoin as a three-part claim
First identify the economic claim: what is the token intended to track, and does the holder have a redemption right or only an expectation of market parity? Second identify the legal and operational claim: who issues it, where, under what terms and through which reserve or redemption arrangement? Third identify the technical object: the exact contract and network.
Scammers exploit readers who check only the name. Two tokens can share a ticker while having different issuers or contracts. A legitimate token can also be imitated by a fake contract.
A no-money depeg drill
Assume a dollar-linked token trades at 0.97 instead of 1.00 while PHP also moves against the US dollar. List the effect on sender purchase cost, provider liquidity, final PHP, recipient timing, redemption and the alternative route. Do not predict when the peg will recover. Decide what evidence is needed and what loss is affordable. For family remittance, waiting may conflict with a real deadline.
Ask a provider which token and network are supported, whether the customer or provider holds it, how conversion is priced, what happens during a depeg, and what the recipient ultimately receives. Clear answers do not eliminate risk, but they reveal whether the route is designed around operations rather than a slogan.
How this connects to market mastery
Advanced participants examine reserve liquidity, redemption arbitrage, market depth, issuer concentration and peg stress. The beginner stack is the same analytical model in simpler form: identify every promise and the mechanism expected to support it.
Key takeaways and check
- A stablecoin is a token with a stabilization design, not automatically a bank deposit or government guarantee.
- Peg, market price and redemption value are different.
- Cross-border utility depends on issuer, network, provider, FX, compliance and final off-ramp.
- A recipient does not need to trade a stablecoin to receive PHP through a compliant route.
Explorer check: Draw the stablecoin stack for a hypothetical transfer and mark the failure that each layer could create.


